India’s real estate market shows two-speed trend as commercial demand stays strong, residential inventory rises: Equirus
Oct 04, 2026
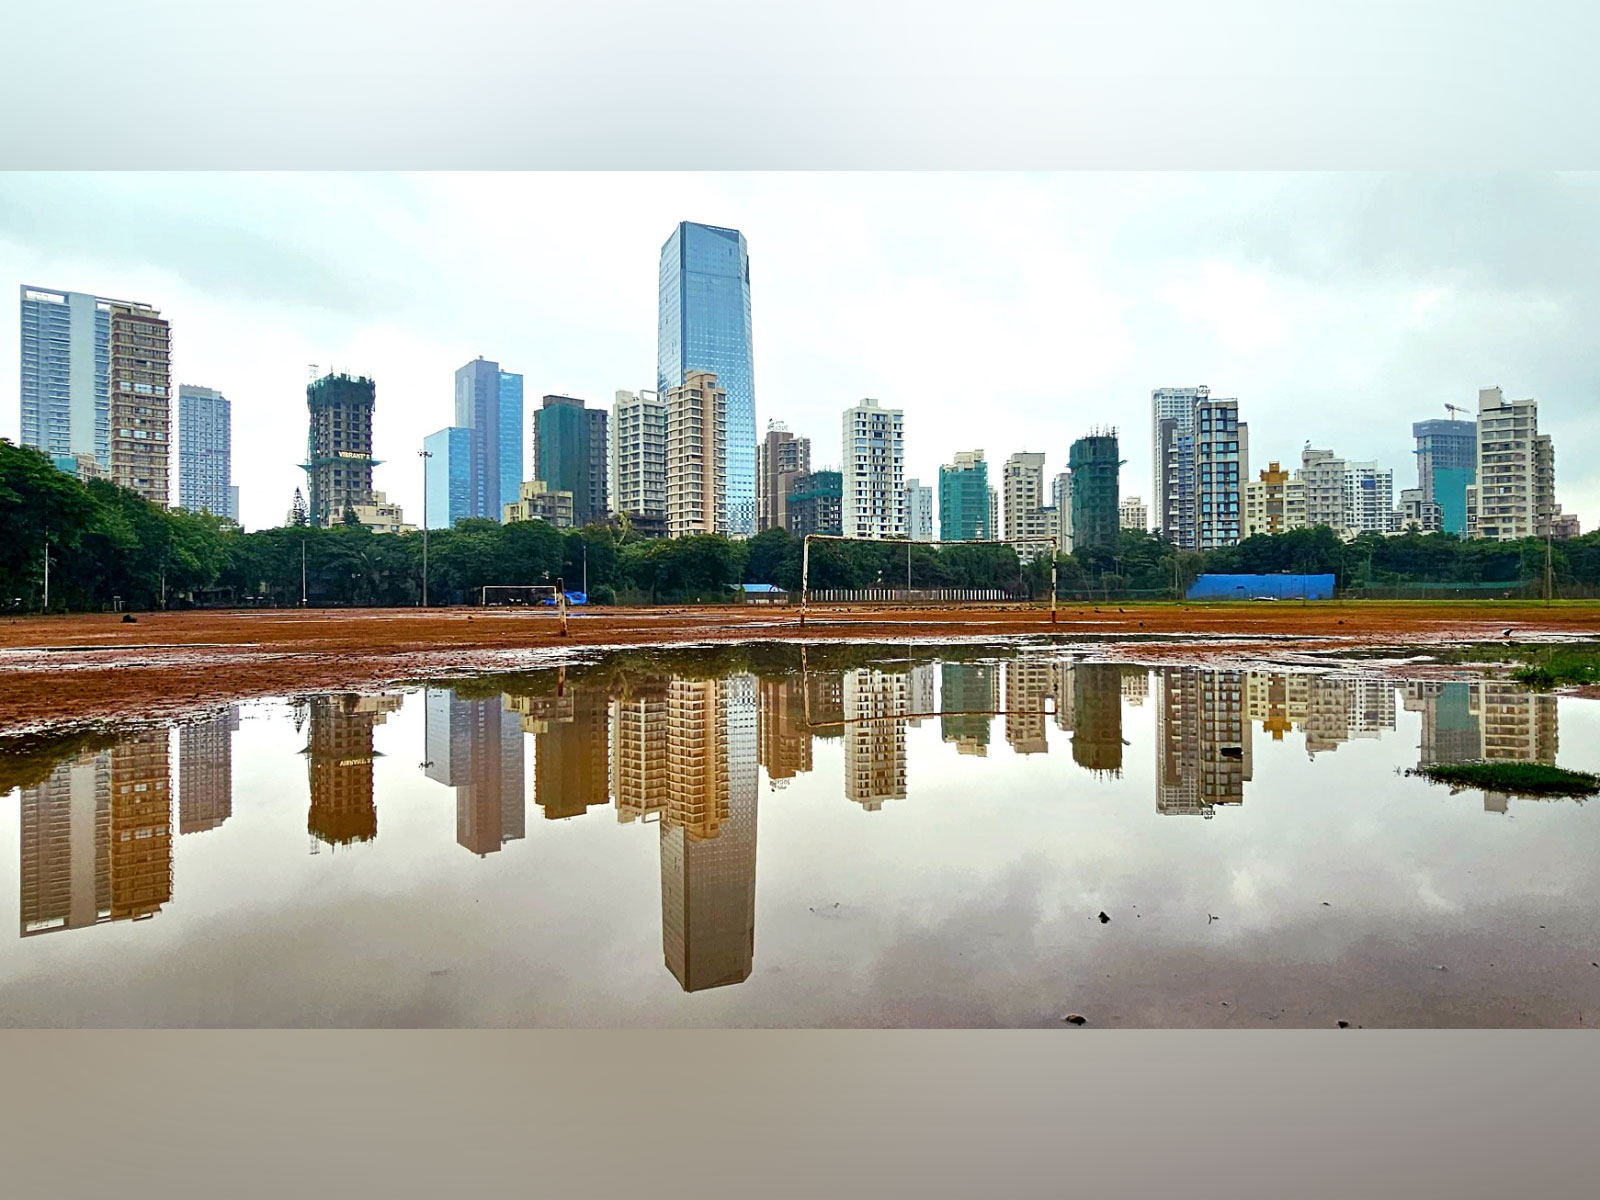
New Delhi [India], October 4 : India’s real estate market is increasingly showing a two-speed trend, with office, flexible workspace and logistics segments recording strong demand even as residential markets see a rise in unsold inventory, report the “Real Estate Tracker - Sept 2026” report by Equirus.
The report said net office absorption across the top seven cities stood at 27.4 million square feet in the first half of 2026, up 2 per cent year-on-year, while office completions declined 10 per cent to 22.2 million square feet. Vacancy fell to a multi-year low of 15 per cent.
Demand from global capability centres (GCCs) remained a key driver, with GCC leasing rising 22 per cent to a record 19.2 million square feet and accounting for 45 per cent of gross office leasing during the period.
The flexible workspace segment also recorded a sharp expansion. Flexible workspace operators leased 191,306 seats in H1 2026, up 68.4 per cent year-on-year and accounted for around 20 per cent of total office leasing during the period, compared with 13 per cent a year earlier.
“Flex transactions in 8 major cities rose 8.4x from 2.2 mn sq ft in 2017 to 18.6 mn sq ft in 2025,” the report said.
The logistics and industrial segment also remained on a strong footing. Leasing across the top eight cities rose 18 per cent year-on-year to a record 36.2 million square feet in H1 2026.
Warehousing accounted for 24.3 million square feet, or 67 per cent of absorption, while third-party logistics (3PL) players leased 12.2 million square feet, with their share rising 64 per cent year-on-year.
In contrast, the residential market showed signs of inventory build-up. Unsold residential inventory across eight major markets rose 4 per cent year-on-year to 525,695 units at H1 2026, while quarters-to-sell increased to 6.0 from 5.8 at the end of 2025.
“Unsold residential inventory in 8 major markets rose 4% YoY to 525,695 units at H1 2026,” the report said.
Ahmedabad recorded the highest inventory overhang at 8.1 quarters, followed by the National Capital Region at 7.6 quarters, according to the report.
Despite the softer absorption trend, developers continued to plan large luxury housing launches. The report said developers were preparing close to Rs 1 lakh crore worth of luxury residential launches in Gurugram in H2 FY27.
The divergent trends point to a real estate market where commercial assets are benefiting from corporate expansion, GCC activity, flexible workspace adoption and logistics demand, while residential markets are facing a gradual build-up in inventory.
The report also noted that the Indian listed REIT universe had expanded from four to six trusts, with listed REITs distributing Rs 3,136 crore in Q1 FY27, more than double the Rs 1,559 crore distributed a year earlier.
Overall, the data in the report indicates that India’s property market is not moving in a uniform direction, with stronger demand and tighter conditions in key commercial segments co-existing with higher residential inventory levels.