SBI targets 14-15 pc credit growth, govt may revisit LTCG tax amid FPI outflows: Chairman CS Setty
Nov 03, 2026
By Saurav Mukherjee
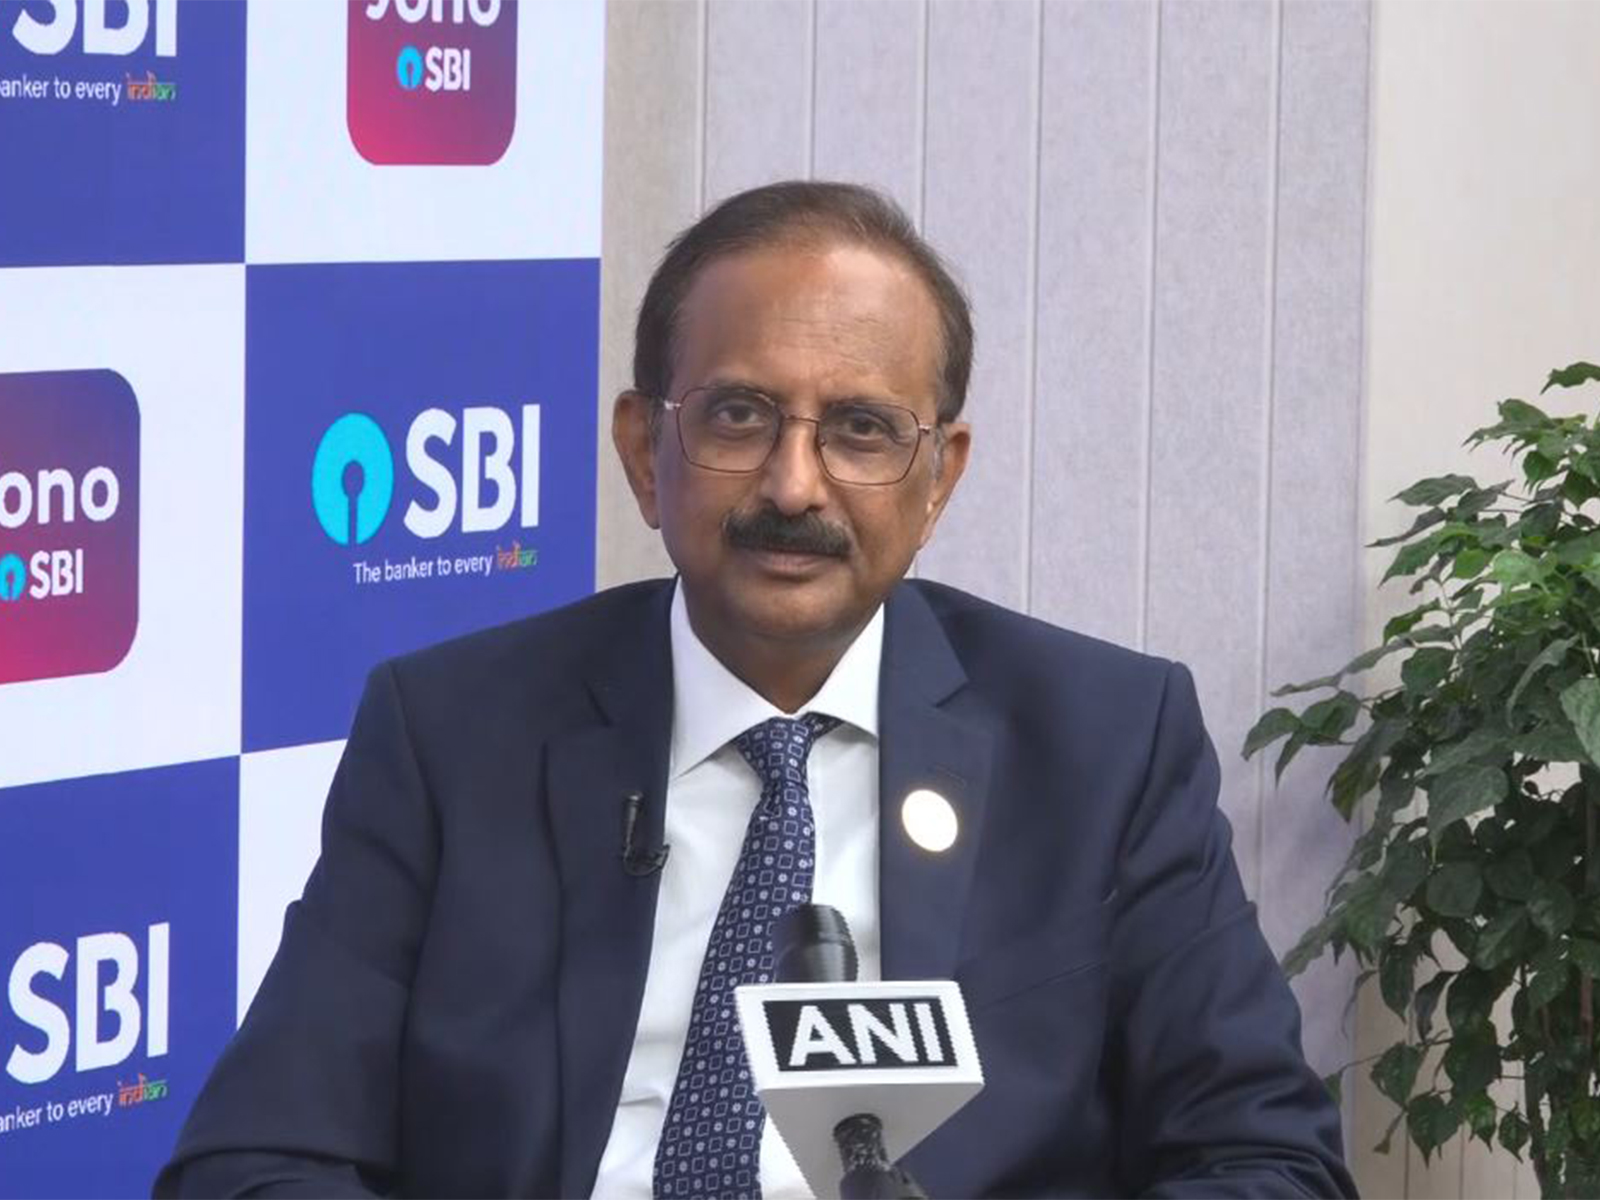
Mumbai (Maharashtra) [India], November 3 : State Bank of India (SBI) Chairman CS Setty said the country's largest lender is targeting credit growth of 14–15 per cent and deposit growth of 10–11 per cent, supported by surplus liquidity of Rs 3.5–4 lakh crore.
Speaking exclusively to ANI following the bank's Q2 FY27 financial results presentation, Setty expressed confidence in sustaining credit growth despite concerns over rising borrowing costs and competition for deposits.
"We have given a 14 to 15% credit growth guidance and a deposit growth guidance of 10 to 11%. And we currently have an excess SLR of more than Rs 3.5 lakh to Rs 4 lakh crore, which provides us with enough liquidity to support credit growth," he said.
Setty highlighted SBI's leadership in current account savings account (CASA) deposits and strong growth in retail term deposits.
"We continue to be the market leader in CASA, and we are seeing robust deposit growth in the retail term deposit segment, around 13 to 14%. I'm sure this should help us support credit growth," he said.
On the potential impact of a further 50-basis-point increase in interest rates, Setty said credit demand from productive sectors, including corporates and micro, small and medium enterprises (MSMEs), is unlikely to be significantly affected.
"I believe that, you know, the productive sectors, whether MSMEs or corporates, will not really be impacted by the rate hike. There could be some moderation in consumption credit, particularly on the discretionary spending side," he said.
On the possibility of rationalising LTCG taxes to address persistent FPI outflows, Setty said the government could examine various policy options.
"FPI outflows have definitely been a concern, and I believe that, you know, the government will look at all the options, including relooking at LTCG," he said.
His remarks came in response to a question citing SBI Research's estimate that scrapping LTCG tax could result in a revenue loss of Rs 40,000–50,000 crore.
On merger and acquisition (M&A) financing, Setty said regulatory relaxations by the Reserve Bank of India (RBI) have enabled SBI to participate more actively in acquisition financing.
"The relaxations mainly came from the Reserve Bank of India, and that has helped us undertake M&A financing," he said.
Explaining the bank's role, Setty said SBI Capital Markets, the bank's subsidiary, handles the advisory component of M&A transactions, while SBI provides financing.
"Financing of mergers and acquisitions also has an advisory component, and that is handled by our SBI Capital Markets subsidiary, while the funding is provided by SBI. We are actively engaged in this," he said.
Addressing cybersecurity concerns following a recent reported data-related incident involving SBI, Setty emphasised that protecting customer information and the bank's information technology infrastructure remains a top priority.
"Cybersecurity is of very, very paramount importance to us, whether it is protecting customer information or our IT assets," he said.
Setty added that the bank is strengthening its cybersecurity protocols through vulnerability assessments, patch management and application programming interface (API) management.
"We are taking all the steps to ensure that our cybersecurity protocols are improved in terms of vulnerability assessments, patch management and the whole range of API management. Everything is being looked into," he said.
"This incident has strengthened our resolve to ensure that our systems are more robust," Setty added.
Meanwhile, SBI's Q2 FY27 net profit rose 14.28 per cent year-on-year (YoY) to Rs 23,038 crore, while operating profit increased 7.28 per cent to Rs 34,226 crore. Net interest income (NII) grew 14.69 per cent YoY to Rs 49,143 crore. The bank's domestic net interest margin (NIM) stood at 3.11 per cent during the quarter, improving by 11 basis points from Q1 FY27.
On the business front, SBI's gross advances grew 17.84 per cent YoY to Rs 52.08 lakh crore, while deposits increased 12.27 per cent to Rs 62.78 lakh crore. SME advances registered a growth of 21.97 per cent, followed by corporate advances at 16.12 per cent and retail personal advances at 14.54 per cent. The bank's gross non-performing asset (GNPA) ratio improved to 1.39 per cent from 1.73 per cent a year earlier, while the net NPA ratio declined to 0.36 per cent from 0.42 per cent.